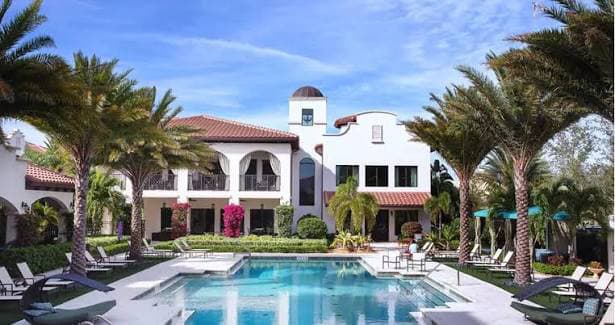
Macroeconomics and Demographic Shifts: The Sun Belt Advantage
Capital concentration across Sun Belt states is driven by structural demographic shifts and favorable tax environments. Between 2020 and 2026, over 4.5 million residents relocated to the Sun Belt from the U.S. Northeast and Pacific coastal markets (such as California, New York, and Illinois).
Key macro drivers supporting this migration include:
- Tax Optimization: Zero personal state income tax in Texas and Florida, combined with competitive corporate tax rates (Arizona at 4.9%, North Carolina at 2.5%).
- Job Growth: Corporate headquarters and operational hubs for major enterprises (including Tesla, Oracle, Caterpillar, and Samsung) continue expanding in Austin, Dallas, Phoenix, and Miami.
- Cost of Living: Lower housing ownership costs relative to coastal gateway cities attract skilled professionals aged 25 to 45.
As a result, population growth across primary Sun Belt metropolitan areas ranges between 1.8% and 2.5% annually, compared to the national average of 0.4%. This influx of high-income households drives sustained demand for modern rental housing and essential neighborhood retail infrastructure.
Performance Dynamics of Class A+ Multifamily and Grocery-Anchored Retail
Under elevated interest rate environments, institutional buyers favor assets capable of re-pricing rents faster than prevailing inflation rates. Class A+ designation requires meeting three main standards: recent construction (post-2021), certified ESG standards (LEED Silver/Gold), automated building management systems, and prime infill locations.
Class A+ Multifamily Assets:
Residential leases feature 12-month terms, allowing landlords to adjust rents annually in line with inflation. In prime submarkets like Austin and Tampa, Class A+ rent growth ranges between 5.5% and 7% per year, while average occupancy rates hover around 96–97%. Acquisition cap rates average between 5.25% and 5.75%, delivering targeted internal rates of return (IRR) of 12–15% under conservative leverage models.
Grocery-Anchored Neighborhood Retail:
Retail centers anchored by national supermarket chains (such as Publix, H-E-B, Trader Joe’s, and Whole Foods) demonstrate high resilience to economic downturns and e-commerce encroachment. Anchor grocers generate foot traffic that directly benefits inline service tenants (pharmacies, restaurants, medical clinics, and personal services).
Anchor leases run 10 to 15 years with built-in annual rent escalations of 2–3% or percentage rent clauses based on gross sales. In-line shop spaces operate under Triple Net (NNN) leases, transferring operating expenses, real estate taxes, and insurance directly to tenants. Cap rates for this asset class average 6.0–6.5%, with portfolio occupancy exceeding 98%.
Transaction Structuring and Mitigating Refinancing Risk
Protecting equity against stringent credit market conditions requires conservative financing structures. Institutional sponsors are avoiding short-term, floating-rate debt and bridge loans, which triggered widespread defaults among undercapitalized Class B/C properties.
International capital entering Class A+ Sun Belt assets utilizes three main financing and legal structures:
- Low LTV Senior Debt: Securing bank or life insurance company financing at conservative 50–55% Loan-to-Value (LTV) ratios with 7- to 10-year fixed interest rates. Debt Service Coverage Ratios (DSCR) are set at a minimum of 1.35x–1.50x to cushion against NOI fluctuations.
- Assumable In-Place Debt: Acquiring properties by assuming legacy mortgages originated in 2020–2021 at fixed rates of 3.5–4.0% with 4 to 5 years of remaining term. This structure elevates cash-on-cash returns to 8–10% annually.
- Tax Structuring via Private REITs and Delaware Statutory Trusts (DSTs): Investors from the Middle East and Central Asia deploy capital through private Real Estate Investment Trusts (REITs). This structure eliminates entity-level corporate taxes provided 90% of taxable income is distributed as dividends. For non-U.S. investors, this setup optimizes dividend withholding taxes and mitigates FIRPTA exposure upon disposition.
Allocating capital into Class A+ real estate across expanding Sun Belt markets preserves underlying asset values while delivering predictable, risk-adjusted distributions in USD.
This material is for general information only and does not constitute legal, immigration, investment, or tax advice. Program requirements and processing practices may change. Individual results depend on the applicant’s circumstances, visa availability, USCIS decisions, and project performance.